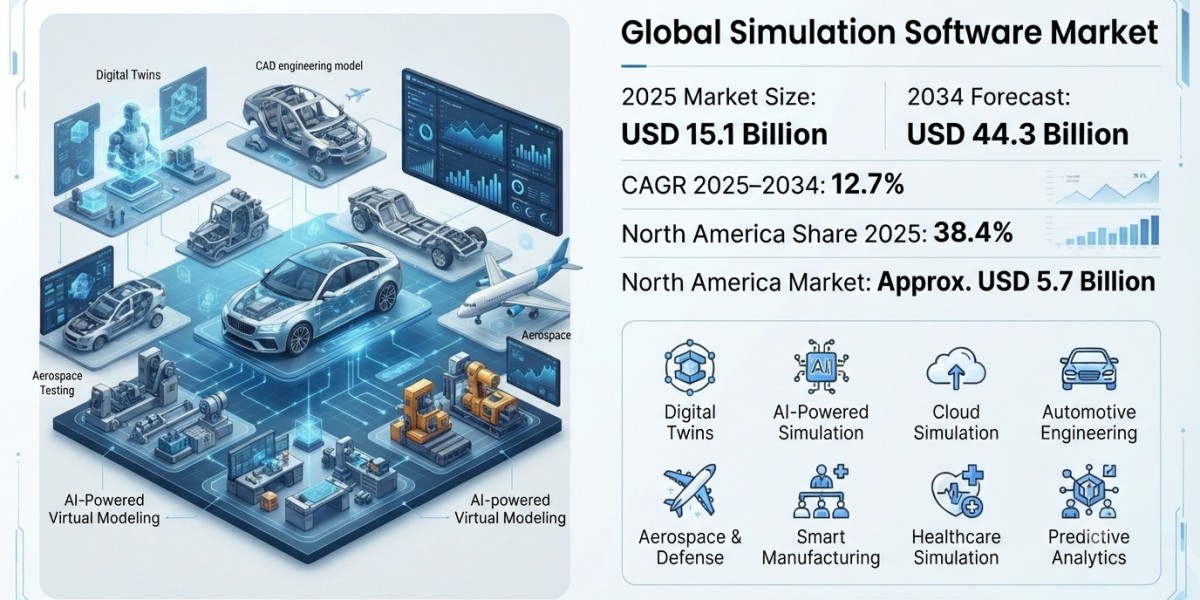
The Global Simulation Software Market Size is projected to reach USD 15.1 billion in 2025 and expand at a compound annual growth rate of 12.7% through 2034, reaching approximately USD 44.3 billion. Simulation software has become an essential digital engineering tool for organizations seeking to model real-world systems, test product behavior, optimize processes, and reduce development risks before committing resources to physical implementation. Growing adoption across automotive, aerospace, healthcare, manufacturing, energy, electronics, and construction industries continues to strengthen the market outlook.
Simulation software enables enterprises to recreate physical systems, operational environments, and business processes within virtual models. Organizations use these platforms for product design, performance testing, engineering validation, manufacturing optimization, training, risk assessment, and predictive analysis. Increasing product complexity and pressure to accelerate time-to-market are encouraging businesses to replace expensive physical prototypes with virtual experimentation, supporting widespread software adoption.
The market is also benefiting from the integration of artificial intelligence, cloud computing, digital twins, high-performance computing, and advanced visualization technologies. Cloud-based simulation platforms are making sophisticated engineering capabilities accessible to organizations without extensive on-premises computing infrastructure. Meanwhile, digital twins are expanding simulation beyond product design into continuous monitoring, optimization, and predictive maintenance of operational assets.
? Looking for Specific Data? Get a Free Customized Sample:
https://dimensionmarketresearch.com/request-sample/simulation-software-market/
Simulation Software Market Overview
Simulation software creates mathematical and digital representations of real-world products, processes, systems, and environments. These applications allow engineers, researchers, designers, and decision-makers to assess different scenarios without exposing physical assets or people to unnecessary costs or risks.
Applications range from computational fluid dynamics and finite element analysis to manufacturing process simulation, electronic system modeling, healthcare training, autonomous vehicle testing, supply-chain optimization, and industrial digital twins. Modern platforms increasingly combine multiple simulation disciplines, allowing organizations to analyze mechanical, thermal, electrical, electromagnetic, fluid, and operational behavior within connected environments.
Key market indicators include:
2025 market value: USD 15.1 billion
2034 projected value: USD 44.3 billion
2025–2034 CAGR: 12.7%
North America holds 38.4% of the market in 2025
North America approaches USD 5.7 billion in 2025
Cloud simulation is expanding enterprise accessibility
Digital twins are broadening real-time simulation use
AI is improving automation and predictive capabilities
Key Findings of the Simulation Software Market
The market is moving from specialized engineering environments toward enterprise-wide digital decision platforms. Manufacturers increasingly deploy simulation during early-stage design because identifying performance problems virtually can reduce costly redesign and prototyping requirements later in the development cycle.
Another important shift involves connecting simulation models with operational data. Rather than using simulation only before production, companies are incorporating models into digital twin environments throughout an asset's lifecycle. This supports condition monitoring, predictive maintenance, operational optimization, and scenario-based decision-making.
Major findings include:
Engineering applications remain central to market demand
Automotive simulation supports EV and autonomous systems
Aerospace requires highly complex virtual validation
Healthcare uses simulation for devices and clinical training
Manufacturing adoption rises with smart factory initiatives
Cloud deployment lowers infrastructure barriers
Digital twins increase lifecycle simulation requirements
AI enhances automated optimization and scenario generation
Simulation Software Market Dynamics
Growth Drivers
One of the strongest market drivers is the rising need to reduce product development time and cost. Physical prototyping can require considerable materials, labor, testing infrastructure, and redesign expenditure. Simulation enables multiple concepts to be assessed virtually before companies manufacture physical prototypes, helping development teams detect weaknesses earlier.
Digital transformation in industrial sectors represents another major growth factor. Manufacturers are introducing connected machines, industrial IoT systems, robotics, automation, and digital twins into production environments. Simulation software helps organizations design and validate these systems while evaluating production capacity, equipment configurations, workflow efficiency, and potential bottlenecks.
The rapid development of electric vehicles and autonomous mobility is also generating new simulation requirements. Automotive companies must model battery behavior, thermal performance, crashworthiness, aerodynamics, power electronics, sensors, advanced driver-assistance systems, and autonomous driving scenarios.
Important growth drivers include:
Rising pressure to shorten product development cycles
Increasing complexity of engineered products
Expansion of digital twin implementation
Growth of electric and autonomous vehicles
Increasing industrial automation investments
Greater emphasis on predictive maintenance
Expanding cloud computing capabilities
Demand for safer virtual testing environments
Market Challenges
Despite strong growth prospects, simulation software can involve significant implementation complexity. Advanced engineering platforms may require expensive licenses, computing resources, specialized technical expertise, and considerable integration with existing engineering systems.
Accuracy is another important consideration. A simulation is only as reliable as its mathematical assumptions, model quality, boundary conditions, and input data. Inaccurate parameters can lead to misleading predictions, making model validation and engineering expertise critical.
Smaller organizations may also struggle with the shortage of professionals capable of operating sophisticated multiphysics and engineering simulation systems.
Key challenges include:
High costs for advanced enterprise platforms
Shortage of specialized simulation professionals
Complex integration with legacy engineering systems
Significant computing requirements for complex models
Need for continuous model validation
Data interoperability concerns across platforms
Cybersecurity risks in cloud-connected environments
Simulation Software Market Trends
Growing Adoption of Digital Twins
Digital twins represent one of the most influential trends affecting the industry. Organizations increasingly create virtual replicas of machines, factories, buildings, vehicles, power systems, and infrastructure. Data from physical assets can be integrated into these virtual environments to simulate operating conditions and anticipate potential failures.
Digital twins are particularly valuable in capital-intensive industries because they enable organizations to test modifications virtually before applying them to physical systems. This can reduce downtime while supporting asset performance management.
AI-Driven Simulation and Generative Engineering
Artificial intelligence is increasingly integrated with simulation platforms to accelerate engineering analysis. Machine learning models can identify patterns across large numbers of simulation runs and help engineers explore promising design configurations more efficiently.
Generative engineering environments can automatically evaluate thousands of design possibilities based on defined performance targets. As computational capabilities improve, AI-assisted simulation is expected to become increasingly important for product optimization.
Expansion of Cloud-Based Simulation
Cloud deployment is changing how companies access advanced simulation capabilities. Organizations can obtain scalable computing power without maintaining extensive local hardware infrastructure. This is particularly useful for simulation workloads requiring substantial computing resources for limited periods.
Key trends shaping market development are:
Digital twins connect models with operational data
AI accelerates optimization and predictive modeling
Cloud platforms provide scalable simulation resources
Multiphysics modeling supports integrated engineering
VR and AR enhance simulation visualization
Real-time simulation supports connected operations
SaaS models improve accessibility for smaller companies
Market Segmentation Overview
The simulation software market can be segmented by component, deployment, simulation type, application, and end-use industry. Software platforms account for the fundamental technology layer, while professional services support implementation, customization, integration, consulting, and technical training.
By deployment, organizations can choose between on-premises and cloud environments. On-premises installations remain relevant for companies managing sensitive engineering information or requiring extensive customization. However, cloud-based solutions are experiencing increasing adoption because of scalability, collaboration benefits, lower infrastructure requirements, and access to high-performance computing.
Simulation types include discrete event simulation, finite element analysis, computational fluid dynamics, electromagnetic simulation, system simulation, process simulation, and multiphysics modeling. Each approach addresses different engineering and operational requirements.
Major end-use markets include:
Automotive and transportation
Aerospace and defense
Industrial manufacturing
Healthcare and life sciences
Energy and utilities
Electronics and semiconductors
Construction and infrastructure
Education and research
Automotive applications include crash testing, aerodynamics, battery simulation, vehicle dynamics, autonomous driving systems, and manufacturing process optimization. Aerospace companies depend heavily on simulation for structural analysis, propulsion, fluid dynamics, thermal management, and flight behavior.
Healthcare applications are expanding across medical device engineering, surgical training, drug development support, anatomical modeling, and hospital workflow optimization. Semiconductor manufacturers similarly rely on advanced modeling to test electronic, thermal, electromagnetic, and manufacturing performance.
Purchase the report for comprehensive details:
https://dimensionmarketresearch.com/checkout/simulation-software-market/
Regional Analysis
North America Simulation Software Market
North America is projected to dominate the global simulation software market with approximately 38.4% market share in 2025, representing a regional market value of about USD 5.7 billion. Strong technology infrastructure, substantial digital transformation investments, and widespread adoption of advanced engineering technologies support regional leadership.
The United States represents a major center for aerospace, automotive technology, defense, semiconductor development, healthcare innovation, software engineering, and industrial automation. These industries require increasingly sophisticated simulation capabilities for designing complex products and testing performance under multiple operating conditions.
Regional growth is further supported by advanced cloud infrastructure, high-performance computing capabilities, AI development, and strong availability of engineering professionals.
Europe Simulation Software Market
Europe represents another important market because of its established automotive, aerospace, industrial machinery, energy, and manufacturing industries. Increasing adoption of Industry 4.0 technologies and digital engineering processes is encouraging companies to integrate simulation into product development and factory optimization.
The transition toward electric mobility and renewable energy systems is also creating requirements for battery, thermal, electrical, structural, and power-system simulation.
Asia-Pacific Simulation Software Market
Asia-Pacific presents substantial long-term opportunities as industrialization, electronics manufacturing, automotive production, infrastructure development, and digital transformation accelerate across major economies.
Rapid development of semiconductor manufacturing, electric vehicles, smart factories, robotics, and renewable energy infrastructure is expanding the number of applications requiring engineering simulation. Increasing availability of cloud computing can further reduce adoption barriers for regional organizations.
Competitive Landscape
The global simulation software market is characterized by established engineering software companies, specialized simulation developers, cloud technology providers, and emerging AI-focused solution vendors. Competition increasingly centers on simulation accuracy, computational performance, interoperability, cloud capabilities, automation, visualization, and support for digital twins.
Major vendors are expanding their portfolios beyond standalone engineering tools toward integrated digital engineering platforms. Product development strategies increasingly emphasize multiphysics capabilities that allow engineers to evaluate interactions between mechanical, electrical, thermal, fluid, and electromagnetic systems within common environments.
Competitive differentiation is increasingly influenced by:
Multiphysics modeling capabilities
AI-powered engineering automation
Cloud and high-performance computing support
Digital twin integration
Real-time simulation functionality
Industry-specific software libraries
Integration with CAD, PLM, and IoT platforms
User-friendly visualization and collaboration tools
Strategic partnerships with cloud infrastructure companies, industrial automation providers, universities, and technology developers are expected to become increasingly important as simulation ecosystems become more interconnected.
Future Market Outlook
The Simulation Software Market is expected to maintain strong expansion through 2034, supported by increasing reliance on virtual development and data-driven engineering. The market's projected rise from USD 15.1 billion in 2025 to USD 44.3 billion by 2034 reflects the growing strategic importance of simulation throughout product and asset lifecycles.
Future simulation environments are expected to become increasingly automated, connected, collaborative, and intelligent. AI could reduce the amount of manual setup involved in defining simulation scenarios, while cloud platforms will enable companies to run computationally intensive models on demand.
Digital twin adoption will further shift simulation from periodic product testing toward continuous operational intelligence. Connected models could simulate asset conditions using real-time information, allowing enterprises to identify potential problems, evaluate corrective actions, and optimize system performance.
Future opportunities will be driven by:
AI-assisted engineering and design optimization
Enterprise-scale digital twin deployments
Autonomous systems validation
Battery and electric vehicle engineering
Smart manufacturing and industrial robotics
Sustainable product development
Cloud-native simulation environments
Real-time infrastructure and energy modeling
Frequently Asked Questions
1. What is the Global Simulation Software Market Size in 2025?
The Global Simulation Software Market is projected to reach USD 15.1 billion in 2025, supported by increasing adoption across automotive, aerospace, manufacturing, healthcare, electronics, energy, and other technology-intensive industries.
2. What will the Simulation Software Market be worth by 2034?
The market is projected to reach approximately USD 44.3 billion by 2034, expanding at a compound annual growth rate of 12.7% from 2025 through 2034.
3. Which region leads the Simulation Software Market?
North America is expected to lead the market in 2025 with approximately 38.4% of global revenue, representing a regional market value of nearly USD 5.7 billion.
4. What is driving demand for simulation software?
Growth is driven by digital twins, AI, industrial automation, virtual prototyping, autonomous systems, cloud computing, EV development, smart manufacturing, and growing requirements for faster product validation.
5. What industries use simulation software most extensively?
Major users include automotive, aerospace and defense, manufacturing, electronics, healthcare, energy, construction, transportation, and research organizations requiring virtual testing and system optimization.
Summary of Key Insights
The Global Simulation Software Market is developing into an important foundation of digital engineering and industrial transformation. Growth from USD 15.1 billion in 2025 to USD 44.3 billion by 2034, at a 12.7% CAGR, reflects increasing demand for faster development, lower prototyping costs, improved product reliability, and data-driven operational optimization.
North America is expected to remain the leading region with 38.4% market share in 2025, while expanding digital transformation across Europe and Asia-Pacific is expected to create additional opportunities.
The market's next stage will increasingly be defined by AI-powered modeling, digital twins, cloud-native simulation, multiphysics engineering, and real-time analysis. As products and industrial systems become more complex, simulation software will continue evolving from a specialist engineering application into an enterprise-wide platform for design, testing, optimization, and strategic decision-making.