
Rare earth markets don't move quietly, and neodymium is proving that again in August 2026. China's neodymium is priced at USD 142,754.20/MT on an FOB basis. India's sitting at USD 142,844.99/MT CIF. Just USD 90.79 apart. That's about as close as two regional rare earth quotes ever get.
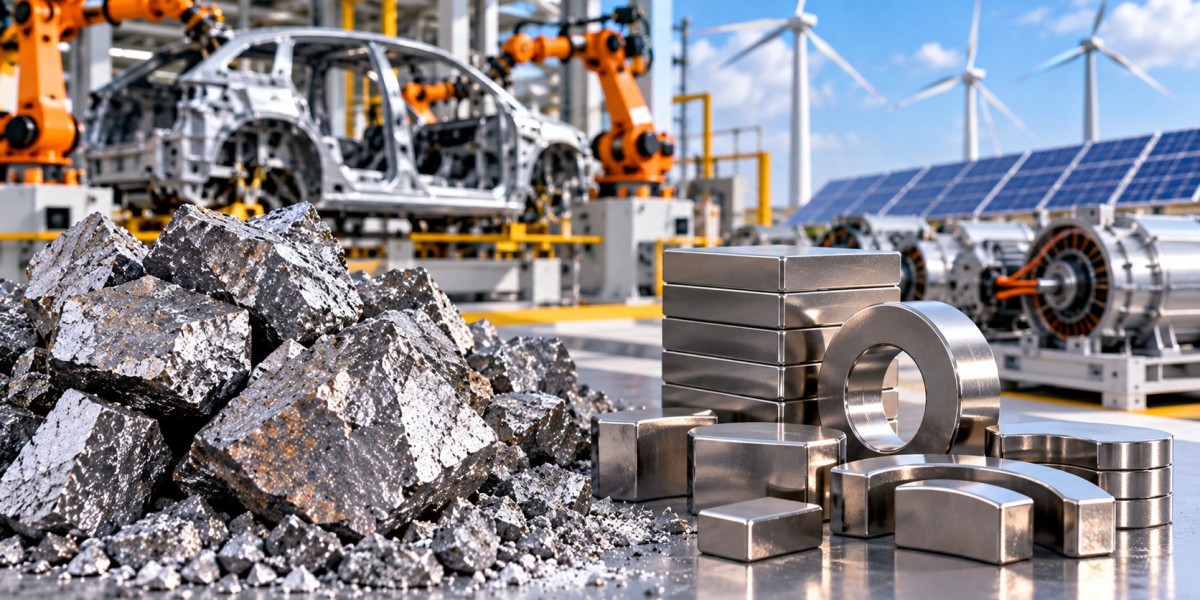
Why should anyone outside a trading desk care? Because neodymium is the metal behind permanent magnets, the kind used in EV motors, wind turbines, and most of the hard drives built in the last decade. Prices here don't stay isolated. They filter straight into clean energy and electronics supply chains within a quarter or two.
Current Neodymium Prices: China vs India
| Product | Region | Incoterm Basis | Price | Last Updated |
|---|---|---|---|---|
| Neodymium | China | FOB | USD 142,754.20/MT | August 2026 |
| Neodymium | India | CIF | USD 142,844.99/MT | August 2026 |
A gap this small, USD 90.79 per metric ton, is unusual for rare earths. Most of the time regional spreads run into the thousands. Not here.
A few things worth flagging:
- China's figure is FOB, meaning the buyer picks up freight and insurance from the port of loading onward.
- India's is CIF, so freight and insurance are already folded into that number.
- Both prices reflect August 2026. Rare earth markets shift fast, so treat this as a snapshot, not a trend line.
Comparing FOB to CIF directly undersells how close these two really are. Add typical freight and insurance costs onto China's FOB number, and the landed cost in China would likely sit above India's CIF rate. Worth sitting with that for a second.
Why Is the Gap So Small This Time?
Good question, and it's one worth pausing on.
China still dominates global neodymium refining capacity by a wide margin. Most of the world's rare earth separation happens there. That typically gives Chinese producers pricing power and keeps their export quotes competitive.
India, meanwhile, imports a large share of its rare earth needs. Normally that pushes landed prices well above China's export rate. But August 2026's numbers show the spread has compressed to almost nothing.
What's driving that? A combination of things, most likely:
- Export policy shifts out of China affecting how FOB pricing gets quoted
- Tighter global supply pushing up the baseline price everyone pays, regardless of region
- Reduced freight cost pressure on the India route this particular month
What's Behind Neodymium Price Movements Generally
Rare earth pricing doesn't follow the same logic as bulk commodities. A handful of factors matter more here than almost anywhere else in the metals space.
Mining and refining concentration. Neodymium production is geographically narrow. China controls most of the processing capacity, so policy decisions there, export quotas, environmental crackdowns, licensing changes, move global prices almost immediately.
Magnet demand. EV production and wind turbine installation both lean heavily on neodymium magnets. Demand growth in either sector tightens supply fast, since there's no quick substitute at scale.
Stockpiling behavior. Governments and manufacturers sometimes build strategic reserves of rare earths. When that happens, it pulls material off the open market and prices react.
Currency and trade friction. Tariffs, export restrictions, and bilateral trade tensions show up in rare earth pricing faster than in most commodities, given how concentrated the supply chain already is.
Quick Q&A: What Buyers Are Actually Asking
Is now a good time to lock in neodymium contracts?
Depends on your risk tolerance, honestly. With China and India pricing this close, there's less obvious arbitrage between the two markets right now than usual.
Should buyers expect this price gap to stay this tight?
Hard to say. Rare earth spreads can widen quickly if China adjusts export policy or if Indian import logistics shift. Tracking monthly data matters more here than in most commodity categories.
Does the small gap mean less supply risk?
Not necessarily. Price convergence reflects cost dynamics, not supply security. India's import dependency hasn't changed just because the price gap shrank this month.
What This Means for Buyers and Investors
For procurement teams sourcing neodymium, the tight spread removes some of the usual incentive to shop between China and India purely on price. Other factors, lead time, supplier track record, contract flexibility, carry more weight when the cost difference is this small.
Investors watching rare earth exposure should note that India's near-parity pricing could reflect growing domestic capability, or it could be a temporary blip tied to this month's freight and policy conditions. Either way, it's a data point worth revisiting next quarter rather than treating as a fixed pattern.
Manufacturers in EV components, wind energy, and electronics should treat this neodymium price trend as a forward signal. Magnet costs tend to show up in finished product margins a quarter or two later, so this is the moment to start adjusting forecasts, not after the fact.
Looking Ahead: Q3 2026 Outlook
Where this goes next isn't obvious. Rare earth markets rarely give clean signals, and neodymium has been especially volatile over the past few quarters.
What seems reasonably likely: the China-India spread stays narrow through Q3 2026 unless there's a meaningful export policy shift out of Beijing or a sudden freight cost change on the India route. Either could reopen the gap quickly.
Buyers locking in long-term contracts right now should factor in that rare earth pricing has a history of sharp, sudden moves. August 2026's tight spread is useful context, not a guarantee of what September or October will look like.
Conclusion
The neodymium price trend for Q3 2026 shows something unusual: China's FOB rate of USD 142,754.20/MT and India's CIF rate of USD 142,844.99/MT, both from August 2026, sitting just USD 90.79 apart. That's a tighter spread than rare earth markets typically produce, and it says something about shifting cost dynamics between the two regions. For anyone in procurement, investing, or manufacturing with neodymium exposure, this is a trend worth watching closely heading into the rest of 2026.
FAQ Section
What is the current neodymium price trend in China and India?
As of August 2026, China's neodymium is priced at USD 142,754.20/MT FOB, while India's sits at USD 142,844.99/MT CIF, a gap of just USD 90.79 per metric ton.
Why is the price gap between China and India so small this time?
Normally India's import dependency pushes its landed price well above China's export rate. This month's near-parity likely reflects a mix of export policy shifts, tighter global supply, and lower freight pressure on the India route, though the exact cause isn't fully clear from pricing data alone.
What drives neodymium prices in general?
Mining and refining concentration in China, magnet demand from EV and wind turbine manufacturing, government stockpiling, and trade policy all play a role. Because supply is so geographically concentrated, even small policy changes move prices globally within weeks.
How reliable is this pricing as a forecast for Q3 2026?
Not very, on its own. Rare earth prices move fast and this spread could widen again if China adjusts export quotas or India's import costs shift. Treat August 2026 figures as a snapshot worth updating monthly, not a locked-in trend.
Who should be paying attention to the neodymium price trend right now?
Procurement teams sourcing rare earth magnets, EV and wind turbine manufacturers planning component costs, and investors tracking rare earth supply chains. Given how fast this market moves, checking updated pricing before finalizing any long-term contract is a reasonable habit to build.