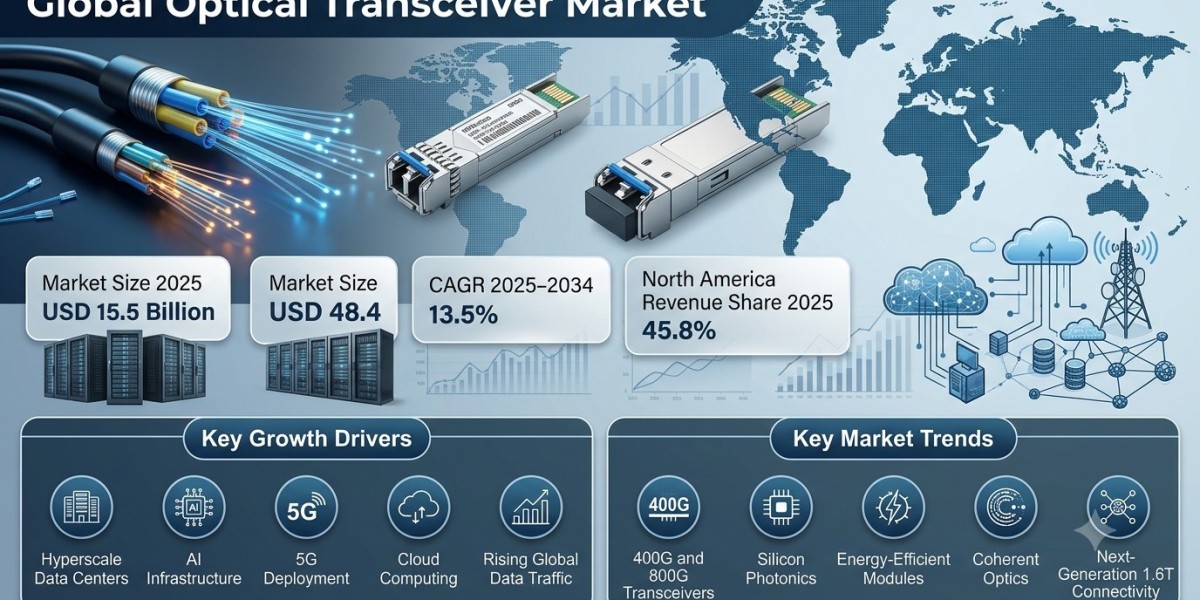
The Global Optical Transceiver Market is entering a high-growth phase as data centers, telecom networks, cloud infrastructure, and high-performance computing systems demand faster and more efficient data transmission. Optical transceivers play a critical role in modern communication infrastructure by converting electrical signals into optical signals and vice versa, enabling high-speed information transfer across fiber-optic networks. The market is estimated to be valued at USD 15.5 billion in 2025 and is projected to reach USD 48.4 billion by 2034, expanding at a strong CAGR of 13.5%.
The rapid expansion of hyperscale data centers, artificial intelligence infrastructure, 5G networks, cloud computing, and bandwidth-intensive applications is accelerating the deployment of high-speed optical connectivity. Enterprises and service providers increasingly require 100G, 400G, 800G, and emerging higher-capacity transceivers to improve network throughput while reducing latency and power consumption. These requirements are transforming optical transceivers from basic networking components into strategically important technologies for digital infrastructure.
Growing internet traffic, video streaming, industrial digitalization, edge computing, and machine-to-machine communication are further strengthening long-term demand. In addition, operators are modernizing legacy network infrastructure with compact, energy-efficient, pluggable optical modules capable of supporting higher transmission speeds without significantly increasing physical network footprints.
Download a Complimentary PDF Sample Report:
https://dimensionmarketresearch.com/request-sample/optical-transceiver-market/
Market Overview
Optical transceivers are compact networking devices used to transmit and receive information through optical fibers. They combine a transmitter and receiver within a single module and are commonly deployed across data centers, telecom networks, enterprise infrastructure, access networks, metropolitan networks, and long-haul communication systems.
The growing dependence on digital services has significantly increased bandwidth requirements across industries. Cloud service providers and data center operators are deploying faster interconnection technologies to support artificial intelligence workloads, large-scale databases, streaming platforms, software-as-a-service applications, and enterprise computing environments.
At a projected 13.5% CAGR from 2025 to 2034, the market is expected to more than triple in value, reflecting the transition toward higher-capacity communication infrastructure. Increasing adoption of 400G and 800G modules represents an important technology shift, particularly within hyperscale data centers where network bottlenecks can directly affect computing performance.
Key Findings
The global optical transceiver market is expected to reach USD 48.4 billion by 2034, compared with USD 15.5 billion in 2025, creating substantial opportunities for component manufacturers, networking companies, semiconductor suppliers, and data center solution providers.
North America is projected to dominate the market in 2025 with a 45.8% revenue share, supported by extensive hyperscale data center infrastructure, strong cloud adoption, telecom modernization, and continued investments in artificial intelligence computing systems.
High-speed optical modules are expected to gain increasing importance as network operators transition toward 400G, 800G, and next-generation transmission standards. Data center applications are also becoming increasingly important because of rising east-west traffic between servers, storage systems, and accelerated computing clusters.
Market Dynamics
The market is influenced by rapidly changing network architectures, evolving communication standards, semiconductor innovation, and increasing bandwidth requirements. Demand is shifting from traditional lower-speed modules toward compact transceivers capable of delivering greater capacity while minimizing power usage.
Network operators are increasingly prioritizing scalability and modularity. Pluggable optical transceivers enable infrastructure providers to upgrade network capacity without replacing complete switching or routing systems, helping reduce deployment costs and improve operational flexibility.
At the same time, greater transmission speed introduces challenges associated with thermal management, signal integrity, power efficiency, manufacturing complexity, and interoperability. Vendors capable of addressing these engineering constraints are likely to strengthen their competitive positioning.
Growth Drivers
Expansion of Hyperscale Data Centers
Rapid construction and expansion of hyperscale facilities remain major contributors to market growth. Cloud computing providers require massive internal connectivity between servers, storage platforms, switches, and computing clusters. Optical connections provide the bandwidth necessary for handling extremely large data volumes.
Artificial intelligence is adding another layer of demand. AI training and inference systems require intensive communication among graphics processing units, accelerators, and storage platforms. Consequently, data center networks are migrating toward increasingly higher-speed optical technologies.
Growth of 5G and Telecom Infrastructure
Deployment of advanced mobile infrastructure is increasing demand for fiber connectivity across front-haul, mid-haul, and backhaul networks. As mobile operators expand 5G capacity, optical transceivers are increasingly required to connect base stations, network aggregation points, and core communication infrastructure.
Rising Cloud and Digital Service Adoption
Enterprises are moving applications, storage, analytics, and computing workloads into cloud environments. This migration generates greater traffic both within data centers and between distributed facilities. Optical transceivers enable network operators to increase throughput without proportionally increasing infrastructure complexity.
Increasing Global Data Traffic
The continued growth of video streaming, online gaming, connected devices, digital payments, remote work platforms, and enterprise applications is creating sustained pressure on network capacity. Fiber-based communication infrastructure has therefore become increasingly critical for reliable high-speed connectivity.
Market Trends
One of the strongest trends is the migration toward 400G and 800G optical modules. These modules are being adopted to support faster switching platforms, high-performance computing environments, and AI-intensive infrastructure.
Another important trend is increasing emphasis on energy efficiency. As data centers operate thousands of network ports, even small reductions in power consumption per transceiver can significantly reduce total energy requirements and cooling expenses.
Silicon photonics is also gaining strategic importance. Integrating optical components with semiconductor manufacturing techniques can improve scalability, reduce component size, and support high-volume manufacturing of advanced optical solutions.
Coherent optical technology is expanding beyond traditional long-distance applications, while compact pluggable architectures are increasingly being explored across metro and data center interconnect environments.
Market Challenges
High-speed optical modules require increasingly complex manufacturing processes and advanced semiconductor components. This can increase development costs and create challenges related to production yield, testing requirements, and supply-chain management.
Thermal performance is another significant constraint. Higher transmission speeds generally increase power consumption and heat generation, creating additional pressure on data center cooling systems and network equipment designs.
Interoperability also remains important. Network operators often use equipment from multiple vendors, requiring optical modules to perform reliably across different switches, routers, communication protocols, and network architectures.
Price pressure represents another challenge. As optical technologies mature, customers increasingly expect higher bandwidth at lower cost per transmitted bit. Manufacturers must therefore balance innovation with manufacturing efficiency and competitive pricing.
Competitive Landscape
The competitive landscape is characterized by continuous innovation in transmission speed, form factor, power efficiency, optical integration, and manufacturing scalability. Companies compete through product performance, reliability, customer relationships, technological differentiation, and compatibility with networking platforms.
Major participants are increasingly investing in silicon photonics, digital signal processing, advanced packaging, laser technologies, and automated manufacturing. Strategic collaboration among optical component manufacturers, semiconductor developers, telecom equipment providers, and cloud infrastructure companies is also becoming more common.
Competition is expected to intensify as 800G adoption expands and next-generation technologies move toward commercialization. Vendors capable of combining high performance with reduced power consumption and competitive production costs are positioned to benefit from future infrastructure upgrades.
Market Segmentation Overview
The optical transceiver market can be segmented based on form factor, data rate, fiber type, wavelength, application, and end-use environment.
By form factor, commonly deployed solutions include SFP, SFP+, QSFP, QSFP28, QSFP-DD, OSFP, and other emerging architectures. The selection of a particular form factor depends on network speed, port density, cooling requirements, and infrastructure design.
By data rate, the market spans lower-speed modules through 10G, 25G, 40G, 100G, 200G, 400G, 800G, and emerging terabit-class solutions. Demand is gradually shifting toward higher-speed categories as network operators upgrade infrastructure.
By application, major segments include data centers, telecommunication networks, enterprise networks, metropolitan infrastructure, and long-distance communication systems. Data centers are particularly important because of the rapid expansion of cloud platforms and AI computing infrastructure.
By fiber type, both single-mode and multi-mode solutions serve different network requirements. Single-mode fiber is widely deployed for longer-distance and high-capacity communication, while multi-mode fiber remains relevant in shorter-distance environments.
Purchase the report for comprehensive details:
https://dimensionmarketresearch.com/checkout/optical-transceiver-market/
Regional Analysis
North America is projected to lead the global optical transceiver market in 2025, accounting for 45.8% of total global revenue. This dominant position is supported by mature communication infrastructure, aggressive adoption of advanced networking technologies, and significant investment in data center expansion.
The region hosts numerous hyperscale cloud operators, large data center campuses, telecommunications companies, networking technology developers, and advanced semiconductor companies. These organizations continuously upgrade their infrastructure to handle rising data traffic, artificial intelligence workloads, cloud applications, and low-latency communication requirements.
Asia-Pacific is also expected to represent a significant growth opportunity as countries expand 5G infrastructure, construct new data centers, increase fiber deployment, and accelerate digital transformation. Rapid growth in cloud adoption, consumer internet usage, manufacturing digitalization, and telecom investment is strengthening regional demand.
Europe continues to invest in data center modernization, fiber infrastructure, cloud services, and next-generation communication networks. Growing requirements for high-capacity enterprise and telecom connectivity are expected to support continued market expansion.
Future Market Outlook
The future of the optical transceiver market will be increasingly shaped by artificial intelligence, hyperscale computing, next-generation mobile networks, and terabit-class communication technologies. Data center networks will require substantially higher bandwidth to support accelerated computing clusters and increasingly distributed cloud architectures.
The transition from 400G to 800G is expected to continue, followed by broader development of 1.6T-class solutions. Network operators will increasingly evaluate technologies based not only on transmission speed but also on power consumption, thermal efficiency, reliability, and cost per bit.
Greater integration between electronics and photonics could transform the design of future networking systems. Silicon photonics, co-packaged optics, advanced packaging, and integrated laser technologies could become increasingly important as conventional pluggable architectures encounter physical limitations.
Frequently Asked Questions
What is the size of the Global Optical Transceiver Market?
The market is estimated at USD 15.5 billion in 2025 and is expected to reach approximately USD 48.4 billion by 2034.
What is the expected growth rate of the optical transceiver market?
The market is projected to expand at a CAGR of 13.5% from 2025 to 2034, supported by data center growth, cloud computing, AI infrastructure, and telecom network modernization.
Which region leads the optical transceiver market?
North America is projected to hold 45.8% of global market revenue in 2025, making it the leading regional market.
What factors are driving demand for optical transceivers?
Major growth factors include hyperscale data center expansion, 5G deployment, cloud computing adoption, increasing internet traffic, AI workloads, and migration toward 400G and 800G networks.
What technologies will shape the future of optical transceivers?
Future development will increasingly focus on 800G and 1.6T modules, silicon photonics, co-packaged optics, advanced semiconductor integration, improved thermal management, and lower power consumption.
Summary of Key Insights
The Global Optical Transceiver Market is positioned for sustained growth as digital infrastructure becomes increasingly dependent on high-speed optical connectivity. The market is projected to increase from USD 15.5 billion in 2025 to USD 48.4 billion by 2034, registering a 13.5% CAGR.
Hyperscale data centers, artificial intelligence infrastructure, cloud computing, 5G deployment, and growing global data traffic are among the strongest demand drivers. North America is expected to remain the leading regional market with a 45.8% revenue share in 2025, while Asia-Pacific presents strong long-term expansion opportunities.
The transition toward 400G, 800G, and future terabit-class connectivity will reshape product development and competitive strategies. Companies focusing on higher transmission speeds, energy efficiency, silicon photonics, advanced integration, and cost-effective manufacturing are likely to play a central role in the next phase of the optical networking industry.